


Gasgoo Munich- The "Golden September, Silver October" selling season is unfolding as scheduled, but the auto market continues to bottom out against a high base.
The China Passenger Car Association (CPCA) expects October passenger-vehicle retail to reach roughly 1.6 million units — down 1.1% from September and off 28.9% from a year earlier, weighed down by an elevated base.
Even as total volumes struggle, bright spots remain concentrated in new-energy vehicles (NEVs). October NEV retail is projected at roughly 1.07 million units, with penetration holding near 66.9% — still underpinning almost two-thirds of the market.
Just how much luster does this "Silver October" actually hold?
1.6 Million Forecast Locked In as Five-Week Ride Resembles a Roller Coaster
Start with the recently closed books on September.
CPCA data shows September passenger-vehicle retail hit 1.618 million units — a 28% plunge from a year earlier, though up 5% from August. Measured against last year's elevated base, the "Golden September" fell short. Internal-combustion models, dragged down by stubbornly high fuel prices, managed just 534,000 retail sales — a drop exceeding 40%. NEV retail reached 1.084 million units, down 16.7% year on year.
Moving into the traditional "Silver October" window, seasonal tailwinds are losing steam. Foot traffic edged up during the National Day holiday but slumped right after. Weak income expectations and wait-and-see sentiment fueled by cutthroat competition show no fundamental signs of easing.
Automakers are equally grounded in their outlook. A CPCA survey in early October found most leading brands cautious about fourth-quarter sales momentum. With most carmakers falling short of 60% of their annual targets through the first three quarters, the final quarter offers room for a volume push. Yet pressure to end price wars and protect dealer margins is limiting how far they can trade price for volume.
All told, October passenger-vehicle retail is penciled in at roughly 1.6 million units — down 1.1% sequentially and 28.9% annually. The market remains stuck in a bottoming phase.
On a weekly basis, October defied the typical steady climb. Instead, it traced a volatile path: a holiday dip, a delivery surge, a brief pullback, and a month-end sprint.
The first week coincided with the National Day break. Brands rolled out Golden Week promotions, and showroom traffic picked up — but most activity was booking orders rather than handing over keys. Daily retail averaged 32,000 units, down 25.0% from a year earlier.
As workdays resumed in the second week, holiday orders shifted into high gear for delivery. Daily retail surged to roughly 58,000 units — a 22.5% year-on-year decline but the strongest sequential gain of the month.
In the third week, expiring promotions slowed the delivery pace. Daily retail slipped to about 47,000 units, a 28.9% annual drop.
By the fourth week, stable deliveries of third-quarter launches kept momentum alive. Daily retail is estimated at around 49,000 units, down 29.0% year on year.
The fifth week brought the customary month-end push as brands stockpiled momentum for the fourth quarter. Daily retail is projected to hit 79,000 units, though the annual decline widened to 33.3%.
For all the activity, undercurrents remain. Across the five weeks, daily retail fell 25.0%, 22.5%, 28.9%, 29.0%, and 33.3% against last year's figures. The high-base headwind blew all month, biting hardest during the final sprint.
On the macro front, data from the National Bureau of Statistics shows total retail sales of consumer goods rose 1.1% in the first nine months of 2026, yet automotive retail tumbled 14.9% — a deep slump in car consumption. September alone saw a 21.2% annual drop in auto retail, with the decline still widening. The National Day crowd effect and trade-in subsidies sparked a brief release of early-month demand, but the fade was fast. Replicating the buzz of past "Silver Octobers" won't come easily.
NEVs Hold Steady at 1.07 Million as Penetration Clings to 66.9%
If the headline numbers carry a chill, the NEV segment remains the most resilient thread in an otherwise split market.
CPCA projects October NEV retail at roughly 1.07 million units, implying a penetration rate of about 66.9%. In September, NEV retail stood at 1.084 million with 67% penetration. While October's rate eases slightly from the quarter-end peak, the move fits typical seasonal patterns — and a near-70% share remains firmly entrenched.
Back-of-the-envelope math puts internal-combustion sales at roughly 530,000 units in October — subtracting 1.07 million NEVs from the 1.6 million total — largely matching September's 534,000. Through the market's swings, NEVs continue to offer a steadier floor. A monthly pace of 1.07 million units is formidable by global standards, keeping China the world's NEV bellwether.
Internal-combustion models face a far grimmer reality. September retail sales of 534,000 units marked a drop exceeding 40%, with volumes barely half those of NEVs. Moving into October, elevated fuel prices continue to drag. The segment leans on holiday traffic and dealer discounts for minor seasonal relief, but that's nowhere near enough to reverse the slide.
With NEVs holding the high ground and internal-combustion models retreating to a shrinking base, this tale of two markets remains the new normal.
NEV confidence rests on twin pillars: order books and supply. The early-October delivery rush largely cleared demand banked during the Golden Week, and several all-new models are waiting in the wings for late-year launches across multiple segments. Yet under the industry's push to curb cutthroat pricing, brands are leaning on product strength and stable pricing rather than bare-knuckle price wars.
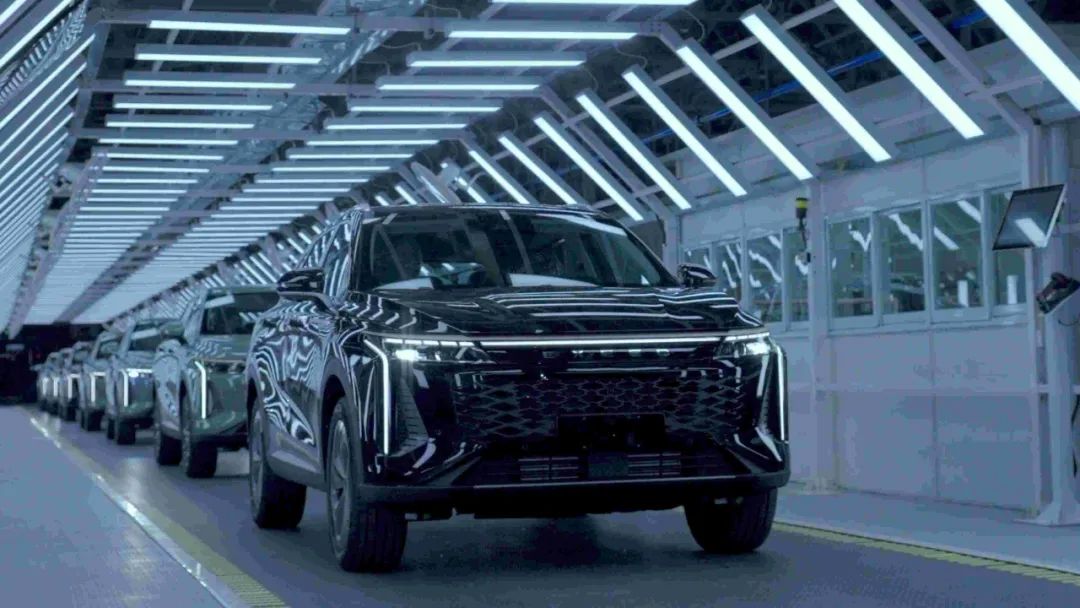
Image source: Chery
Still, NEVs aren't entirely immune to headwinds. CPCA notes the segment's growth has hit a plateau. The journey from unveiling to blind booking, pre-sales, official launch, and final delivery is stretching out. Longer wait times for hot models are slowing the retail cadence. Against a high base, the industry is shifting from broad-based gains to a battle for depth.
As for where penetration goes next, early bets are being placed. Cui Dongshu, secretary-general of the CPCA, expects the domestic market to bottom out and recover in 2027, with retail growth averaging around 2%. A last-minute rush before NEV purchase-tax incentives expire should provide a tailwind. Combined with lithium carbonate prices nearly halving from their 2026 peak — easing battery costs — the final burst of policy-driven demand and lower expenses will open new room for EV consumption.
Looking ahead to the fourth quarter, year-end volume pushes, fresh models, and policy tailwinds should continue to prop up the NEV market. For automakers, the "Silver October" test is no longer just about moving more metal — it's about securing a foothold in the electric transition. The 66.9% mark isn't a finish line; it's simply the latest footnote in the rewiring of China's growth engine.


